
 By Spanos Theodoros · · Updated
The Greek Golden Visa has become internationally associated primarily with the acquisition of real estate. However, for an investor considering Greece as part of a broader residence and investment strategy, purchasing property is not the only available option.
The Greek legal framework also provides for financial investment routes, including the placement of at least €500,000 in a fixed-term deposit with a Greek credit institution.
This represents a fundamentally different approach: instead of acquiring and managing an asset in the Greek real estate market, the investor opts to place capital in a bank deposit which, provided it meets the statutory requirements and is maintained in accordance with them, may serve as the basis for the granting of a residence permit.
The real question, therefore, is not whether a fixed-term deposit is “better” than purchasing property. It is which investor profile this option is best suited to.
A Different Approach to Investment-Based Residence
The choice of an investment route should not be based solely on the amount of capital required.
For an international investor, equally important considerations include the form in which capital will be invested, the investment horizon, liquidity needs, the desired exposure to particular markets and, of course, the personal and family objectives associated with obtaining a residence permit.
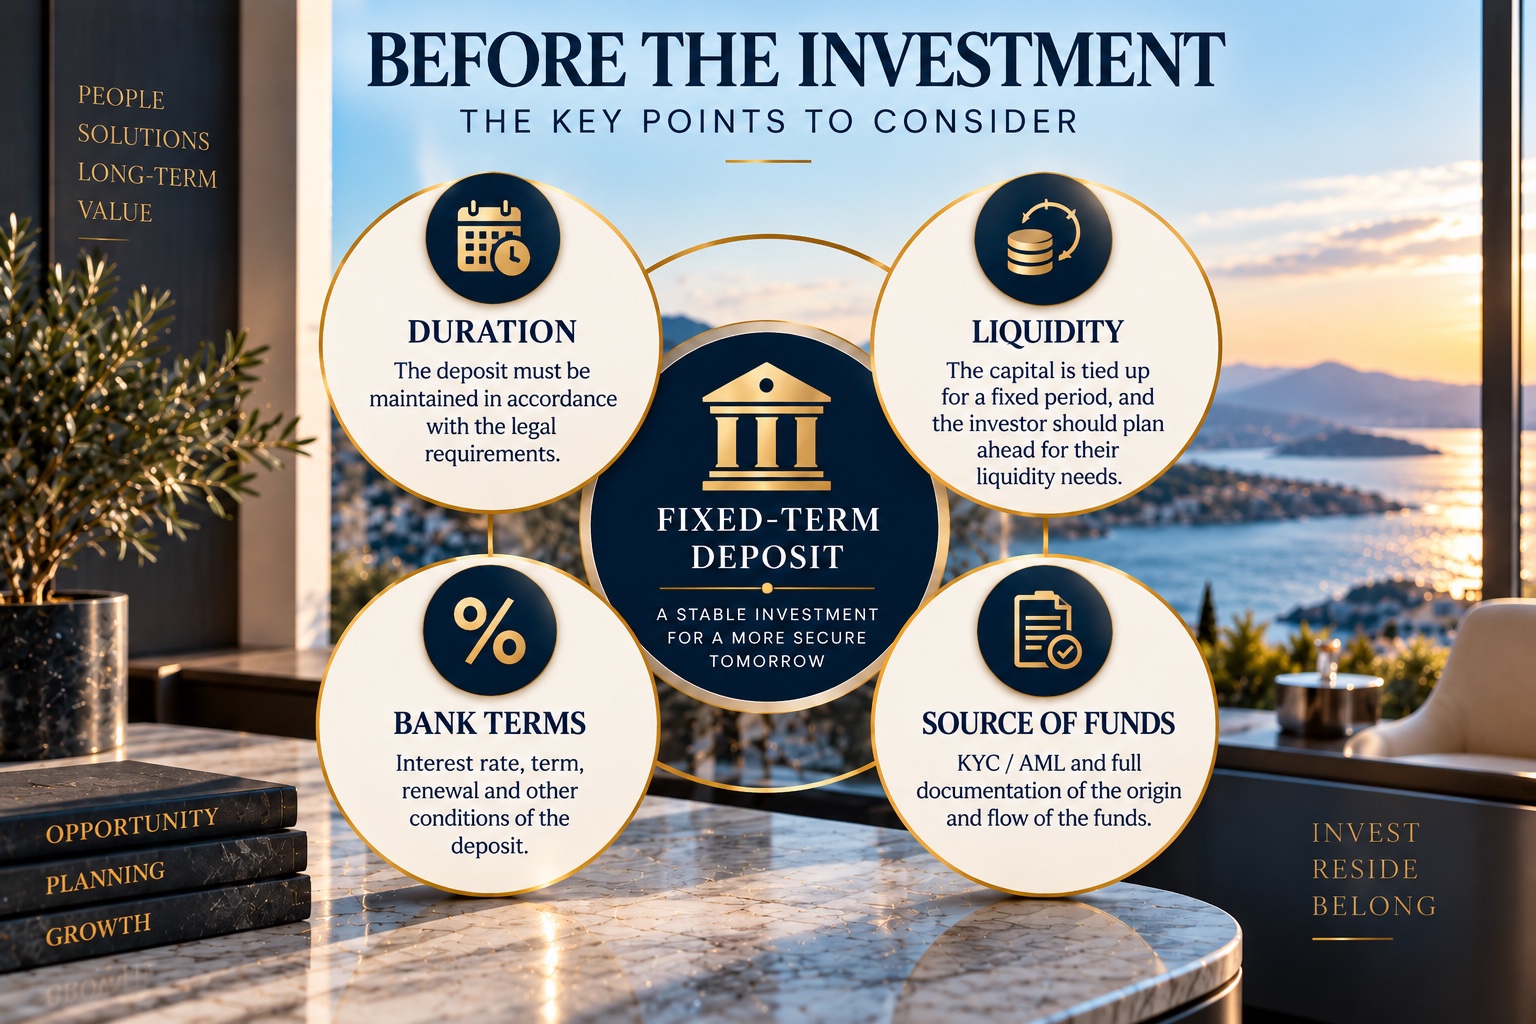
In the case of a fixed-term deposit, the law requires a minimum amount of €500,000 deposited with a credit institution established in Greece, for a term of at least one year and subject to a standing renewal instruction. Both the making and the continued holding of the investment are certified by the credit institution.
This structure fundamentally distinguishes a fixed-term deposit from an investment in real estate.
Which Investors Might Find This Option Suitable?
A fixed-term deposit may be particularly attractive to an investor who views a Greek residence permit primarily as part of international residency planning, without also seeking to acquire property in Greece.
It may also appeal to someone who prefers a more standardized financial investment and does not wish to become involved in searching for and selecting a property, conducting legal and technical due diligence, completing a notarial transaction or subsequently managing the asset.
This does not mean that either investment is objectively superior to the other.
It means that they serve different investment priorities.
Real Estate or a Fixed-Term Deposit?
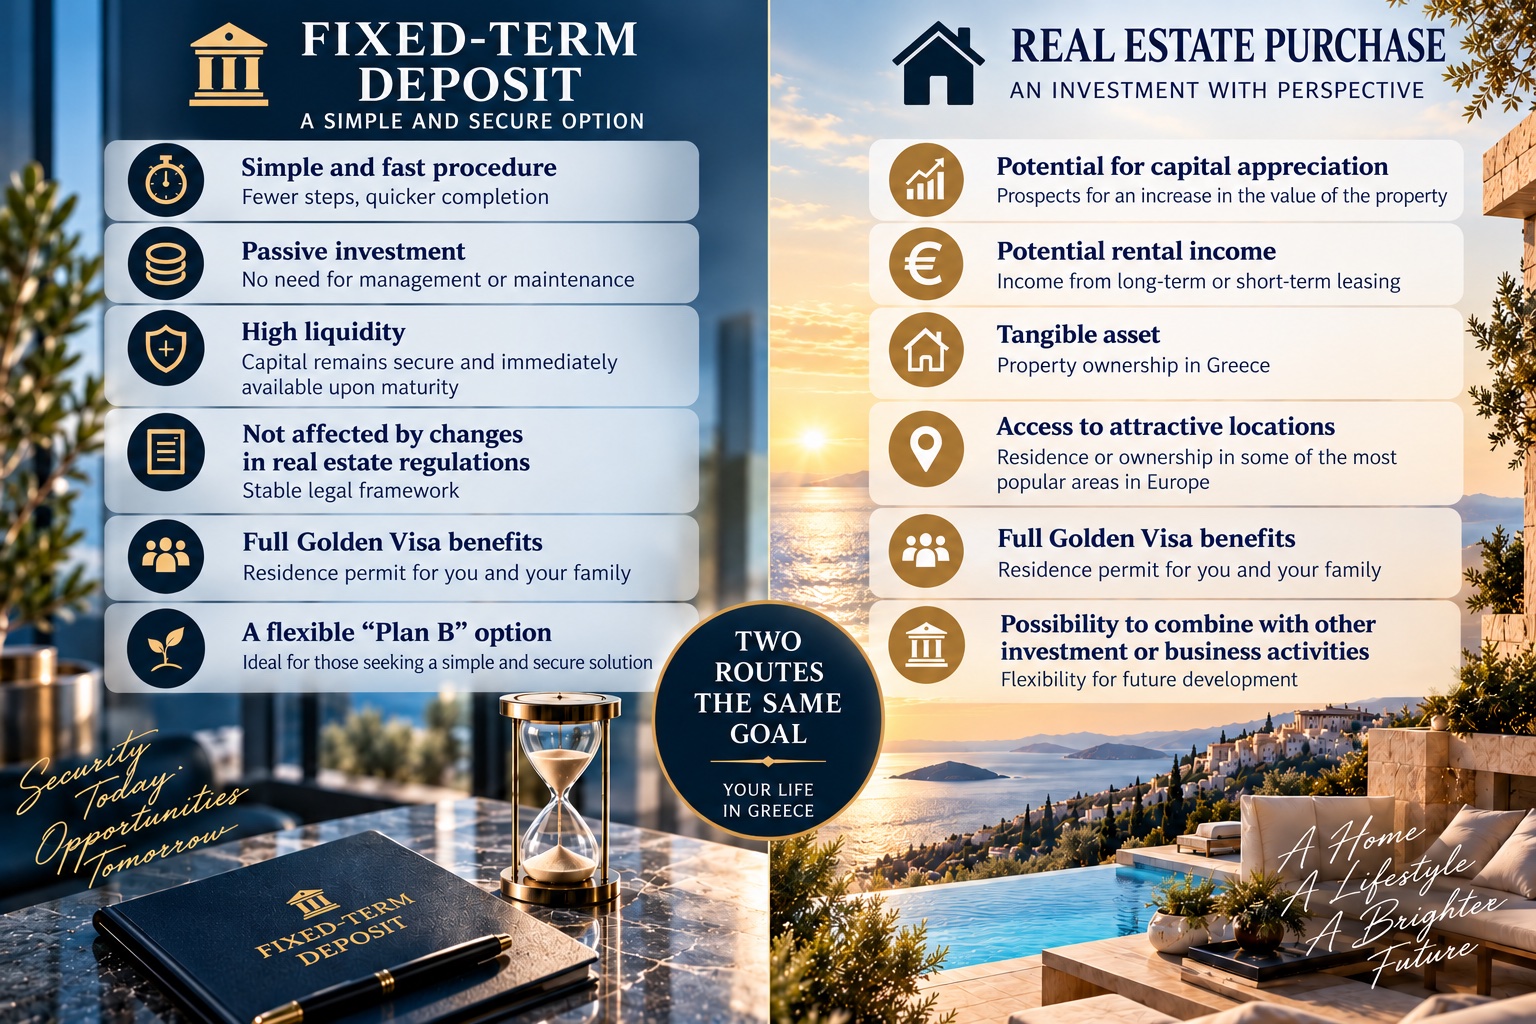
Investing in real estate can serve several objectives at once. The investor acquires a tangible asset that may be intended for personal use or, where permitted under the applicable legal framework, for commercial exploitation. At the same time, the investor gains exposure to the future performance of the Greek real estate market.
This, however, entails a different set of factors to assess: location, actual market value, legal and technical condition, taxation, transaction costs, maintenance expenses, opportunities for use or exploitation, and future resale value.
A fixed-term deposit separates the investment decision from these considerations. It does not require the selection of a particular property or the assumption of the obligations associated with ownership.
For an investor who does not wish to gain exposure to the real estate market, this distinction may be decisive.
On the other hand, a fixed-term deposit does not offer the features that may make property attractive as an investment, such as personal use, potential capital appreciation or the possibility of generating income through its permitted exploitation.
The decision should therefore be based on the investor’s objectives, not merely on the amount invested.
Simplicity Does Not Mean an Absence of Scrutiny
Compared with a real estate purchase, the structure of a fixed-term deposit may appear more straightforward. However, this does not mean that the process is limited to simply transferring €500,000 to a Greek bank.
Preparing for the banking process is a critical part of the investment.
Greek credit institutions apply Know Your Customer (KYC) and Anti-Money Laundering (AML) procedures and examine, among other matters, the customer’s identity and financial profile, as well as the origin and movement of the funds.
For an international investor, documenting the source of funds is therefore not a secondary formality.
Savings, business income, dividends, investment returns, or proceeds from the sale of a shareholding or another asset may each require different supporting documentation. Moreover, what matters is not only the lawful origin of the funds but also the ability to clearly trace their banking movements up to the point at which the investment is made.
Timely preparation of the banking documentation may therefore be just as important as the choice of investment route itself.
The Critical Issue of Liquidity
One of the most important considerations before choosing a fixed-term deposit is the continued holding of the investment capital.
The initial deposit of €500,000 is not sufficient on its own. The investment must be maintained in accordance with the statutory requirements, and its continued holding must be certified by the credit institution.
This also changes the fundamental question the investor should ask.
It is not simply:
“Do I have €500,000 available?”
Rather, it is:
“Am I able and willing to keep €500,000 in this form of investment as part of my overall financial planning?”
For an investor with substantial liquidity needs, business obligations or other investment opportunities, committing this capital must be carefully weighed.
The predictability of the deposit structure is an advantage only if it is compatible with the investor’s overall wealth management strategy.
Returns: A Consideration, Not the Primary Reason for Choosing This Route
A fixed-term deposit is an interest-bearing banking product. The interest rate, term, method of interest payment and other contractual conditions are determined by the credit institution and the conditions prevailing when the deposit is placed.
For this reason, there is no fixed rate of return that can be regarded as an inherent feature of this investment route.
The investor should assess the bank’s actual offer at the time of investment and distinguish between two separate matters:
the return on the bank deposit and the usefulness of the investment as part of the investor’s residency planning.
In many cases, the second consideration may be more important than the first.
A Bank Deposit Is Not a Risk-Free Investment
A fixed-term deposit should not be presented as “risk-free”, “100% safe” or a fully guaranteed investment.
Before placing such a substantial amount of capital, the investor should assess the credit institution, the deposit terms, its duration, the interest rate, the consequences of possible early termination and the applicable deposit protection framework.
Of particular importance is the fact that the general European deposit guarantee framework provides protection only up to a specified limit per depositor and per credit institution. Accordingly, the €500,000 investment requirement for residence permit purposes must not be confused with the amount of statutory protection afforded to bank deposits.
Risk assessment therefore remains necessary even where the chosen investment is a banking product.
What Happens to the Interest?
Interest earned on the fixed-term deposit constitutes income and must be assessed separately for tax purposes.
For an international investor, its tax treatment may depend, among other things, on the investor’s tax residence and the application of any Double Taxation Agreement between Greece and the investor’s country of tax residence.
For this reason, the tax implications of the deposit must be examined on an individual basis, rather than in isolation from the investor’s overall international tax profile.
A Residence Permit and Tax Residence Are Not the Same
This distinction is particularly important for international investors.
A residence permit and tax residence are separate concepts governed by different criteria.
Obtaining a residence permit through investment should not, in itself, be considered to automatically result in the transfer of the investor’s tax residence to Greece.
If the investor is also considering physically relocating to Greece, transferring tax residence or entering a special tax regime such as the Greek Non-Dom regime, these matters must be analyzed separately as part of comprehensive tax and wealth planning.
When Might This Not Be the Right Choice?
The €500,000 fixed-term deposit route is not suitable for every investor.
Someone who intends to purchase a home in Greece for personal use in any event may conclude that acquiring property serves several objectives simultaneously.
Similarly, an investor seeking exposure to the Greek real estate market, potential capital appreciation or income from the permitted exploitation of property may prefer a real estate investment strategy.
A fixed-term deposit may also be unsuitable for someone who wishes to keep most of their capital immediately accessible or frequently reallocate it among different investments.
This is why comparing the available options should not be limited to “how much each one costs”.
The question is which option best aligns with the particular investor’s overall strategy.
The Value of Making the Right Choice
The €500,000 fixed-term deposit offers a different investment route for those considering Greece as part of broader residence, mobility and wealth management planning.
Its defining feature is not merely that it allows the investor to proceed without purchasing property.
Rather, it offers a different investment structure that may better suit investors who wish to separate the decision to obtain a residence permit from the decision to acquire real estate.
For other investors, property may remain the most suitable solution.
Making the right choice therefore requires an assessment of the investor’s profile, liquidity needs, investment horizon, the origin and structure of the funds, and the investor’s personal, family and tax objectives.
In this context, choosing the appropriate investment route is not simply a procedural decision aimed at obtaining a residence permit. It forms part of a broader strategic plan for the investor’s presence in Greece and Europe.
SF Legal Law Firm provides comprehensive legal support to international investors, from the initial assessment of the appropriate investment route and preparation for banking procedures to the completion of the investment and the residence permit application process.